Asset‑Based Finance Partners: A Practical Guide for Businesses
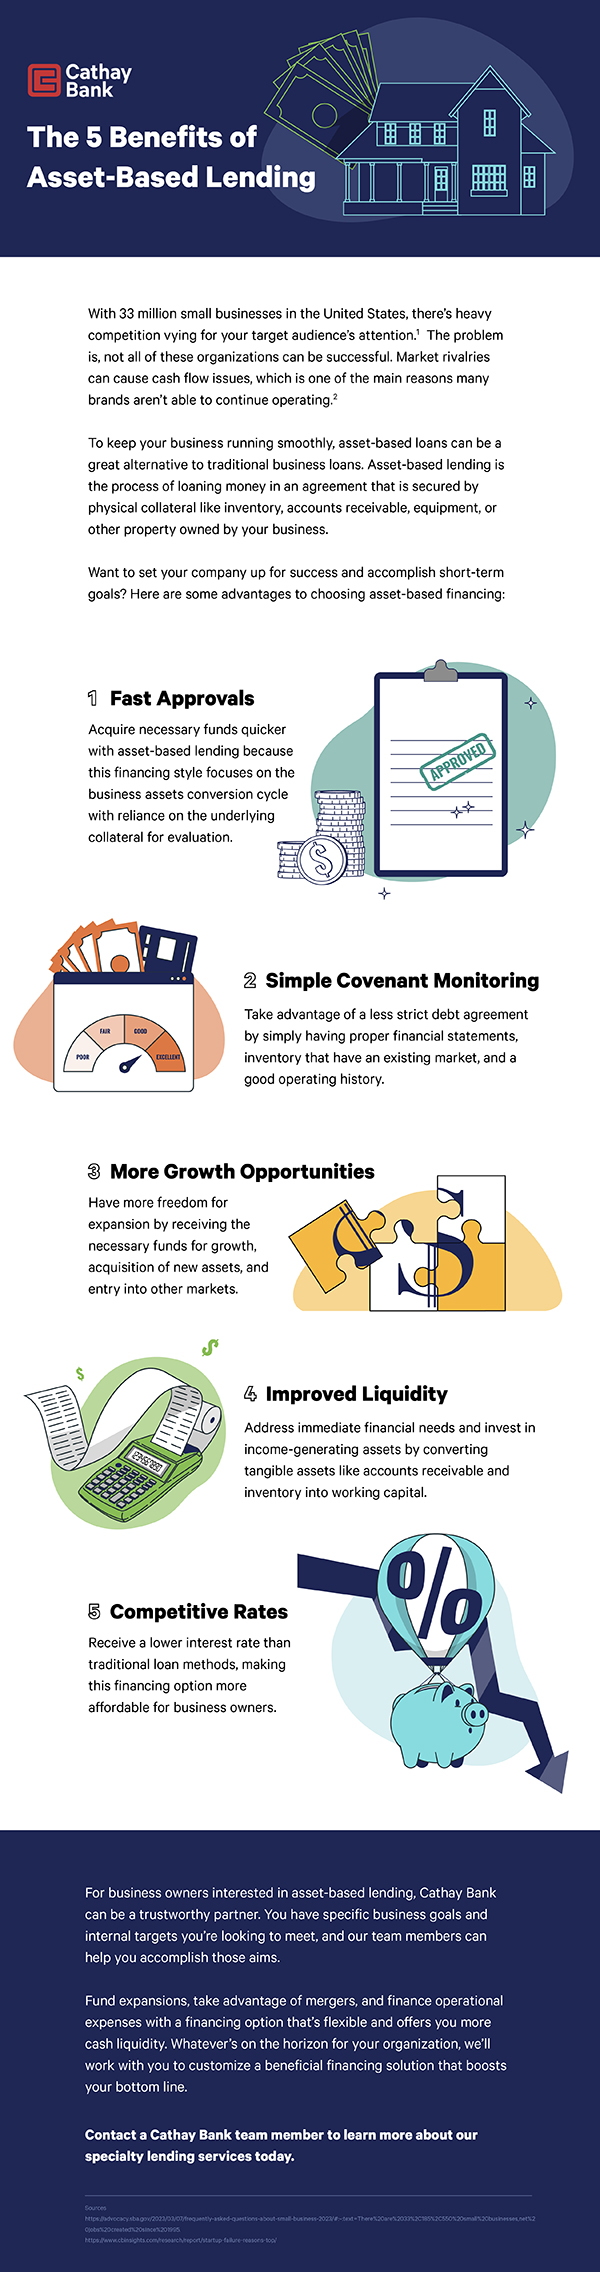
When cash flow feels tight but the business still needs to grow, many companies turn to asset‑based finance partners for a reliable bridge. Unlike traditional bank loans that hinge on credit scores, these partners offer capital secured by inventory, receivables, or equipment—assets you already own. This guide unpacks how asset‑based financing works, the types of partners you’ll meet, and the steps to secure the right deal.
What Is Asset‑Based Financing?
At its core, asset‑based financing is a loan or line of credit backed by a company’s tangible or receivable assets. The lender evaluates the value of the collateral and offers a percentage of that value, usually between 60% and 90%. The process typically follows these stages:
- Collateral assessment and valuation
- Credit evaluation of the borrowing entity
- Terms negotiation (interest rate, maturity, covenants)
- Closing and disbursement
Why It Matters for Growing Businesses
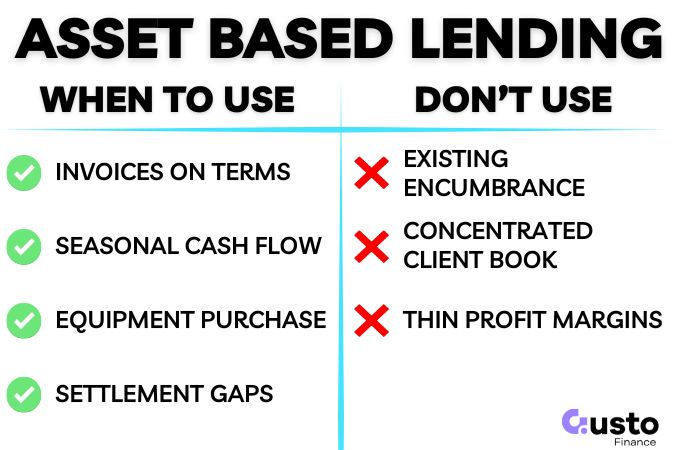
Asset‑based finance shines when:
- Sales cycles are long, leaving working capital thin.
- Inventory or receivables are the primary drivers of growth.
- Credit history is limited or shaky, but the business has valuable collateral.
Types of Asset‑Based Finance Partners
Not every finance provider operates the same way. Here are the key player categories:
1. Dedicated Asset‑Based Lenders
These firms specialize exclusively in asset‑based lending. They often have deep expertise in valuing specific asset classes—like wholesale inventory or accounts receivable. Because of this focus, they can offer faster turnaround times and more tailored underwriting.
2. Traditional Banks with Asset‑Based Suites
Large banks that maintain a dedicated asset‑based lending division combine the stability of a bank with the flexibility of an asset‑based product. They may offer broader collateral types, but their processes can be more bureaucratic.
3. Private Equity & Venture Capital Partners
Some private equity firms provide asset‑based facilities as part of a broader investment strategy. These partners can bring additional strategic guidance but may demand stricter covenants or equity participation.
How to Choose the Right Partner
Picking the right finance partner is a mix of financial fit and relationship chemistry. Here are the critical checkpoints:
Assess the Collateral Match
- Ensure the partner has experience valuing the exact assets you bring.
- Check for flexibility in handling mixed collateral portfolios.
Examine the Credit and Underwriting Process
- Ask about the typical timeline from application to funding.
- Verify that the partner’s risk assessment aligns with your business model.
Review the Cost Structure
- Interest rates vary based on collateral type and credit profile.
- Look for additional fees—appraisal, due diligence, or early repayment penalties.
Consider Post‑Funding Support
- Some partners provide cash flow forecasting, inventory management consulting, or receivables acceleration services.
- Ask whether the lender can help you optimize collateral value over time.
The Application Process in Detail
Below is a step‑by‑step overview of what most asset‑based lenders require:
Step 1: Collateral Audit
Prepare detailed lists of inventory, accounts receivable aging reports, and equipment appraisals. Accuracy here speeds approval.
Step 2: Financial Snapshot
Provide recent financial statements, cash flow projections, and a narrative explaining how the funds will be used.
Step 3: Negotiation of Covenants
Common covenants include:
- Collateral Coverage Ratio: Minimum value of collateral relative to the loan.
- Liquidity Ratio: Requirement to maintain a certain level of liquid assets.
- Reporting Requirements: Quarterly or monthly updates on inventory levels or receivable collections.
Step 4: Closing & Disbursement
Once terms are agreed, the lender releases the funds. For lines of credit, the borrower can draw as needed, subject to the credit limit.
Common Misconceptions Debunked
1. “I’ll lose ownership of my assets.” – The collateral remains yours; you simply grant a security interest until the debt is repaid.
2. “This is only for large corporations.” – Many lenders serve small and medium enterprises, especially those in manufacturing or wholesale sectors.
3. “The rate is fixed.” – Asset‑based rates are typically variable, tied to benchmarks like LIBOR or the prime rate.
Best Practices for Maintaining a Healthy Relationship
- Keep inventory records current; inaccurate valuations can trigger covenant breaches.
- Maintain transparent receivables reporting; lenders often monitor collection efficiency.
- Revisit covenants annually; as your business evolves, renegotiating terms can free up capital.
Frequently Asked Questions
- What assets can be used for collateral? Inventory, accounts receivable, equipment, and in some cases, real estate or even intangible assets like intellectual property.
- How quickly can I get funded? With a dedicated asset‑based lender, funding can occur in as little as 7–10 business days; traditional banks may take 30 days or more.
- Do I need a strong credit history? Not necessarily. The lender focuses on the value of the collateral, so a modest credit score can be offset by high‑quality assets.
- What happens if I default? The lender has the legal right to seize the collateral and sell it to recover the outstanding balance.