Explore Low‑Down‑Payment Options for Island Home Loans
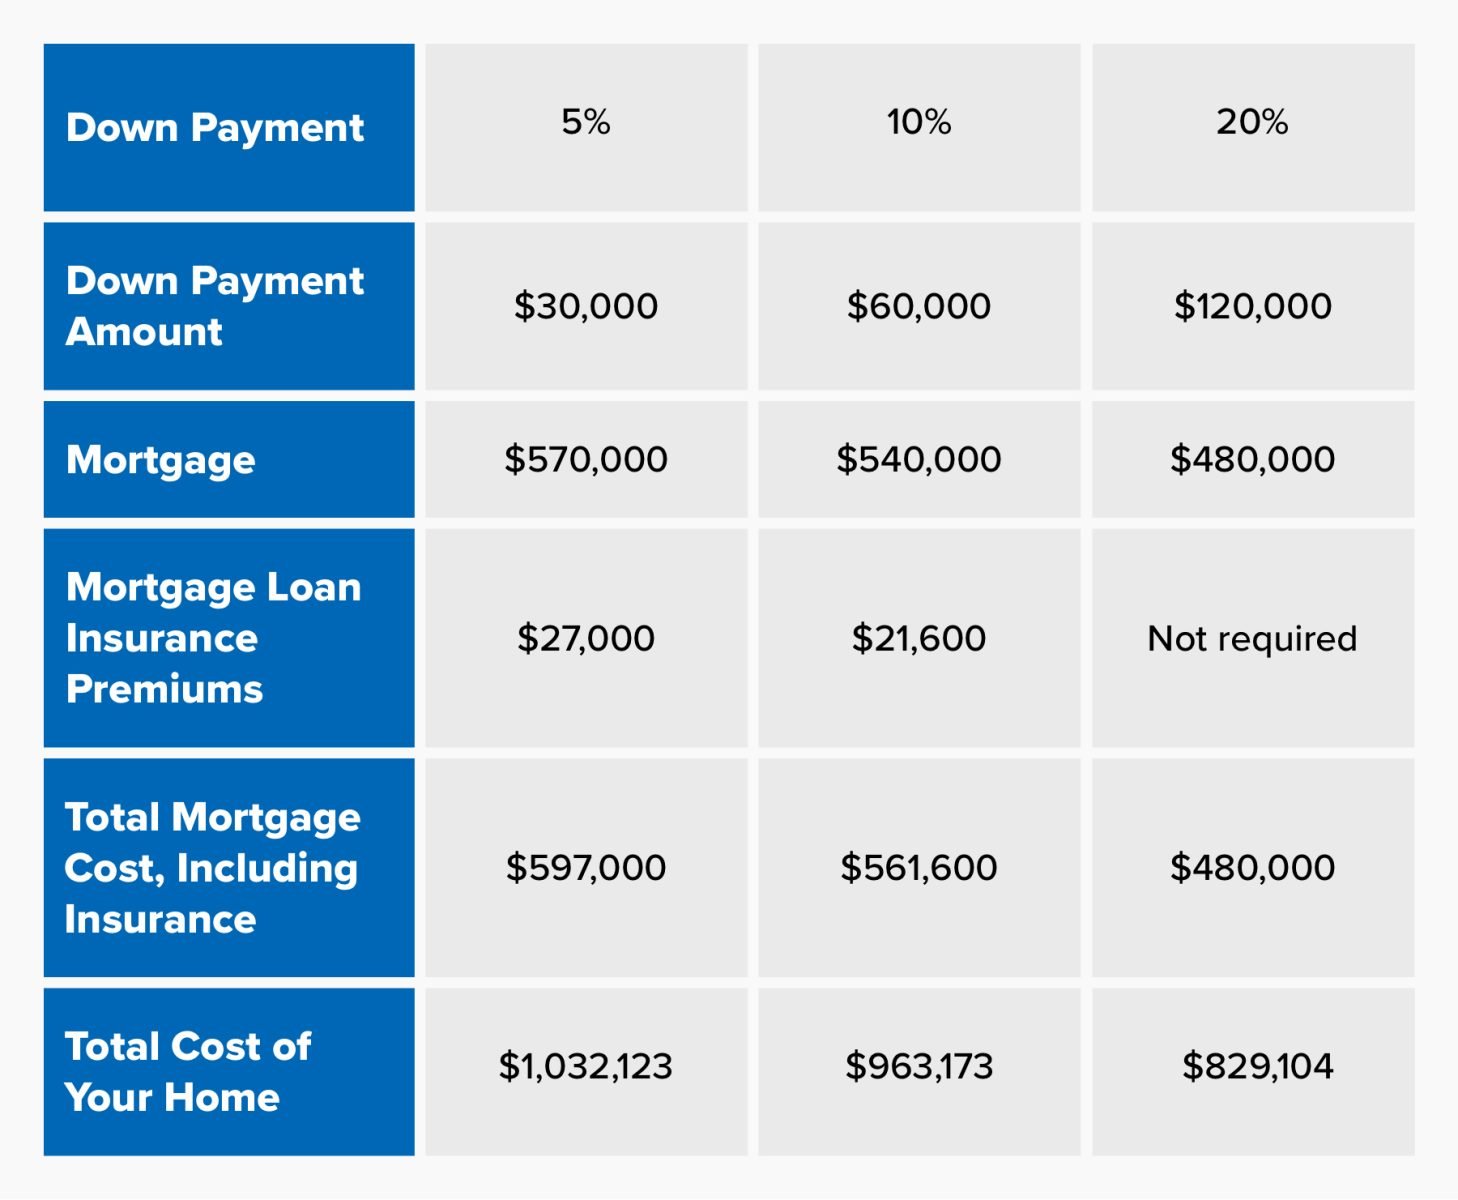
If you’ve set your sights on a coastal retreat, the idea of a hefty down payment can feel like a roadblock. Luckily, many lenders now offer island home loan programs that let you put down as little as 3 % of the purchase price. In this guide we’ll unpack why those low‑down‑payment options exist, which programs are most common, and how you can position yourself to take advantage of them.
Why Low Down Payments Matter on the Islands
Island real estate often carries a premium because of limited inventory and higher construction costs. For most buyers, that means the total price can quickly climb into the six‑figure range. A traditional 20 % down payment would therefore require a six‑figure cash outlay—something most families simply don’t have on hand.
Low‑down‑payment loans help bridge that gap, allowing you to secure a mortgage while you continue to build savings or invest elsewhere. They also enable first‑time buyers to enter the market sooner, which can be a strategic move if property values are on an upward trend.
Typical Low‑Down‑Payment Programs
- FHA 203(b) Loans – Backed by the Federal Housing Administration, these loans accept as little as 3.5 % down. They’re popular for both primary residences and second homes on islands, though the property must meet certain safety and habitability standards.
- VA Loans – If you’re a qualified veteran or active‑duty service member, the Department of Veterans Affairs can finance a home with zero down payment, provided the loan amount stays within the VA’s regional limits.
- USDA Rural Development Loans – Many island communities qualify as “rural” under USDA guidelines. These loans also offer zero‑down financing, but they require that the home be the borrower’s primary residence.
- State‑Specific First‑Time Buyer Programs – Several coastal states run their own initiatives that cap down payments at 5 % or less. These often come with reduced closing‑cost assistance and flexible credit‑score thresholds.
Each of these programs has its own eligibility quirks, but they share a common goal: to lower the cash barrier to homeownership.
How to Qualify and What to Expect
Even though the down payment is small, lenders still scrutinize other aspects of your financial picture. Here’s a quick checklist of what they typically look for:
- Credit Score – Most low‑down‑payment loans prefer a score of 620 or higher. FHA loans are a bit more forgiving, while VA and USDA loans can work with scores in the high‑500s if other factors are strong.
- Debt‑to‑Income Ratio (DTI) – Lenders usually cap DTI around 45 %. A lower ratio improves your chances of approval and may lower your interest rate.
- Stable Income – Consistent employment or documented self‑employment income is essential. Lenders will ask for recent pay stubs, tax returns, and sometimes a profit‑and‑loss statement.
- Reserves – While the down payment is minimal, lenders often want to see a few months of mortgage payments tucked away as a safety net.
Once approved, you’ll likely encounter a mortgage insurance premium (MIP) for FHA loans or a guarantee fee for VA loans. Those costs are built into your monthly payment, so factor them into your budget.
Tips for Reducing Up‑Front Costs
Even with a low down payment, closing costs can still add up. Consider these strategies to keep the total out‑of‑pocket expense manageable:
- Seller Concessions – Negotiate for the seller to cover a portion of the closing costs. Many island sellers are willing to do this if it speeds up the transaction.
- Discount Points – Paying a small amount upfront to lower your interest rate can be worthwhile if you plan to stay in the home for several years.
- Local Grants – Some municipalities offer home‑buyer assistance grants that specifically target island communities. A quick check with the county housing office can uncover hidden resources.
- Roll Closing Costs Into the Loan – Some lenders allow you to add certain fees to the principal balance, spreading the expense over the life of the loan.
Remember, each option has trade‑offs. For example, rolling costs into the loan increases the total interest you’ll pay, while discount points require cash up front.
Choosing the Right Lender for Island Purchases
Not all lenders have the same expertise when it comes to island properties. Look for institutions that have a dedicated “coastal” or “island” loan specialist. These professionals understand the nuances of flood‑zone insurance, transportation logistics, and local appraisal challenges.
Ask prospective lenders about their experience with the specific island you’re targeting. A lender familiar with the local market can often expedite the underwriting process and may offer more competitive rates.
FAQ
Can I use a low‑down‑payment loan for a vacation home?
Generally, FHA loans require the property to be your primary residence, but VA and some state programs do allow second homes. Always check the program’s occupancy rules before you apply.
Do low‑down‑payment loans mean higher interest rates?
Not necessarily. While mortgage insurance adds to the monthly payment, the base interest rate can be comparable to conventional loans, especially for borrowers with strong credit.
What happens if I can’t afford the mortgage after a few years?
Many low‑down‑payment programs offer refinancing options that can reduce your payment. Additionally, some lenders provide hardship assistance, but it’s crucial to communicate early if you foresee payment difficulties.
Are there income limits for USDA loans on islands?
Yes, USDA loans have both income and location eligibility criteria. Typically, you must fall below 115 % of the area’s median income, and the property must be in a designated rural area, which many islands qualify as.