How New York Taxes 401(k) Withdrawals and What to Plan For
When you take a 401(k) withdrawal in NY, the tax bill can feel like a maze of federal rules, state specifics, and timing tricks. New Yorkers often assume the same rules that apply nationwide will dictate their state tax, but New York adds its own layer of rates, exemptions, and penalties. Understanding how these pieces fit together early can save you from an unexpected surcharge and help you shape a withdrawal strategy that aligns with your retirement goals.
Federal vs. State Tax on 401(k) Distributions
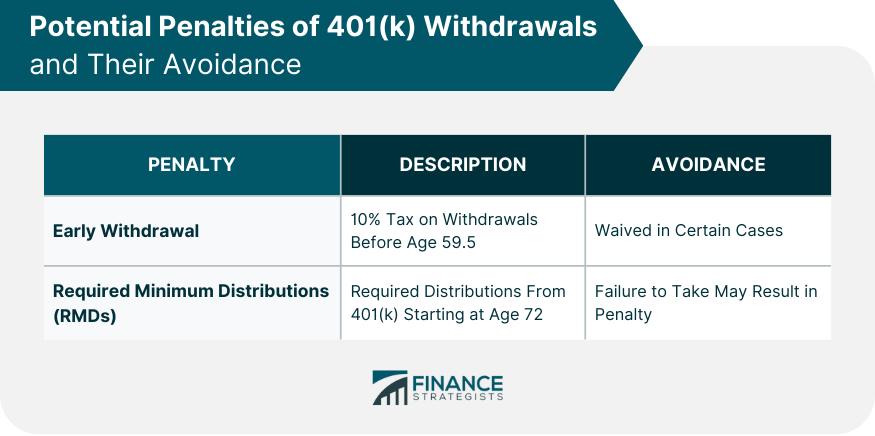
At the federal level, any pre‑tax 401(k) distribution is treated as ordinary income. That means the amount you pull out is added to your taxable earnings for the year and taxed at your marginal federal rate. Most retirees also face a 10 % early‑withdrawal penalty if they’re under 59½, unless they qualify for an exception such as disability or a qualified domestic relations order.
New York mirrors the federal approach by also counting the distribution as ordinary income, but it applies the state’s progressive tax brackets on top of the federal amount. The state rates range from roughly 4 % to 10.9 % for the highest earners. Because the state does not offer a separate early‑withdrawal penalty, the 10 % federal surcharge is the only “extra” charge for early access.
New York Specific Rules You Need to Know
While the basic income treatment is the same, New York has a few quirks that affect your net take‑home:
- Residency matters. If you move out of New York after the distribution, you may still owe state tax on the amount earned while you were a resident.
- Required Minimum Distributions (RMDs). Beginning at age 73 (as of recent federal changes), you must take an RMD each year. New York does not exempt RMDs, so they count fully toward your state taxable income.
- Roth 401(k) conversions. Converting a traditional 401(k) to a Roth triggers taxable income in the conversion year, but future qualified withdrawals from the Roth are tax‑free at both federal and state levels.
These points mean that timing and the type of account you hold can dramatically shift your overall tax picture.
Penalties, Exceptions, and Safe Harbors
The 10 % federal early‑withdrawal penalty is the main financial sting for younger retirees. However, New York recognizes several federal exceptions without adding its own penalty. Some common scenarios include:
- Qualified higher education expenses for you, your spouse, children, or grandchildren.
- First‑time home purchases (up to $10,000).
- Medical expenses that exceed 7.5 % of your adjusted gross income.
If you qualify, you still report the distribution as income, but you can claim the exception on your federal return, which in turn reduces the amount New York sees as taxable.
Strategic Planning Tips for New Yorkers
Here are practical steps to keep your tax hit manageable when you tap into retirement savings:
- Spread withdrawals across years. Instead of pulling a lump sum, consider taking smaller amounts over several tax years to stay in a lower bracket.
- Time conversions wisely. If you expect your income to drop in a future year, schedule a Roth conversion then to lock in a lower tax rate.
- Leverage the “tax‑free” window. After you reach age 59½, you can withdraw without the federal penalty. Use this window to fund large expenses before RMDs begin.
- Coordinate with charitable giving. Directly transferring a distribution to a qualified charity (a qualified charitable distribution, QCD) can satisfy RMD requirements while excluding the amount from taxable income, which also benefits New York tax calculations.
- Consult a NY‑based tax professional. State tax nuances, especially around residency changes, often require personalized advice.
Remember, the goal isn’t just to minimize tax—it's to align withdrawals with your cash‑flow needs, investment strategy, and legacy plans.
Impact of Moving In or Out of New York
If you plan to relocate, the timing of your withdrawal can change the state tax story. New York taxes you on any 401(k) distribution you receive while you’re a resident, even if you later become a non‑resident. Conversely, if you become a New York resident after a distribution, the state generally does not retroactively tax that income.
For those contemplating a move to a lower‑tax state, consider postponing large withdrawals until after you’ve established residency elsewhere. However, be mindful of the “part‑year resident” rules that could still attribute a portion of the distribution to New York based on the date of the withdrawal.
Key Takeaways for a Smart Withdrawal Strategy
Balancing federal and New York tax obligations requires a mix of timing, account selection, and awareness of exceptions. By spreading out distributions, using Roth conversions strategically, and staying alert to residency implications, you can keep more of your retirement nest egg working for you.
Frequently Asked Questions
Do I still owe New York state tax if I withdraw a 401(k) after moving out of the state?
Generally, no. New York taxes only the portion of the distribution taken while you were a resident. Once you become a non‑resident, future withdrawals are subject to the tax rules of your new state.
Can I avoid the 10 % early‑withdrawal penalty in New York?
The penalty is federal, not state. If you meet a recognized exception—such as paying qualified medical expenses or buying your first home—you can avoid the 10 % surcharge, and New York will follow suit without adding its own penalty.
Are Roth 401(k) withdrawals tax‑free in New York?
Yes, qualified Roth withdrawals—those taken after age 59½ and at least five years after the first contribution—are exempt from both federal and New York state income tax.
What’s the best age to start taking 401(k) withdrawals in New York?
While you can begin at 59½ without penalty, many experts suggest waiting until after you hit the RMD age (currently 73) if you don’t need the money. Delaying lets your investments grow tax‑deferred and may keep you in a lower tax bracket.