How to Navigate Idaho Central Credit Union: A Complete Guide
If you’re new to the world of credit unions, Idaho Central Credit Union (ICCU) can feel both welcoming and a bit mysterious. This guide cuts through the jargon, showing you who can join, what products are on offer, and how the cooperative spirit translates into everyday banking perks. By the end, you’ll know whether ICCU fits your financial goals and how to make the most of its services.
Who Can Join Idaho Central Credit Union?
Membership isn’t limited to a single employer or a narrow demographic. ICCU opens its doors to anyone who lives, works, or attends school in Idaho, plus immediate family members of current members. Some neighboring states also qualify if you own property there. This broad eligibility reflects the credit union’s community‑first ethos, allowing friends and relatives to share the same financial home.
To join, you typically need a modest opening deposit—often $5 or $10—into a new savings account. Once that’s set, you receive a member‑only debit card, online access, and the right to vote on board elections. Remember, you’re not just a customer; you’re an owner with a voice in the cooperative’s direction.
Products and Services Overview
ICCU’s portfolio mirrors that of larger banks while retaining the personal touch of a local institution. Here’s a quick snapshot:
- Checking and Savings Accounts – Low‑fee checking, high‑yield savings, and youth accounts that teach money basics.
- Loans – Auto, home, personal, and student loans, many with competitive APRs and flexible repayment options.
- Credit Cards – Rewards cards focused on everyday spending, plus a secured option for building credit.
- Investment Services – IRAs, brokerage accounts, and financial planning through partnered advisors.
- Business Solutions – Treasury management, merchant services, and commercial loans for small to mid‑size enterprises.
Each product is designed with member savings in mind, meaning lower fees and better rates than many for‑profit counterparts.
Fees, Rates, and What to Expect
Transparency is a hallmark of credit unions, and ICCU is no exception. Most checking accounts waive monthly maintenance fees if you maintain a minimum balance or set up direct deposit. Overdraft protection is optional, and the fee—when applied—is generally lower than the industry average.
Interest rates on savings and CDs tend to sit a few percentage points above national averages, especially for longer‑term deposits. Meanwhile, loan APRs benefit from the cooperative’s not‑for‑profit status, often undercutting big‑bank offers. Still, rates fluctuate with market conditions, so it’s wise to lock in a rate when you’re comfortable with the terms.
Digital Banking Tools
In today’s fast‑paced world, a robust mobile experience is non‑negotiable. ICCU’s app lets you check balances, transfer funds, and deposit checks with a simple snap of your phone’s camera. The platform also supports bill pay, budget trackers, and alerts that keep you informed about low balances or upcoming payments.
If you prefer a desktop view, the online portal mirrors the app’s functionality and adds a secure messaging system for direct contact with a representative. Both channels employ multi‑factor authentication, ensuring your data stays safe without sacrificing convenience.
Community Involvement and Member Benefits
Beyond banking, ICCU invests heavily in the communities it serves. From sponsoring local youth sports teams to offering scholarships for Idaho students, the credit union’s outreach programs reinforce its cooperative roots. Members often receive discounts at participating local businesses, reinforcing a cycle of local support.
Another perk is the annual member dividend—essentially a share of the credit union’s earnings returned to you as a credit on your account. While not guaranteed, many members view it as a tangible reminder that they’re part of a collective success story.
How to Get Started
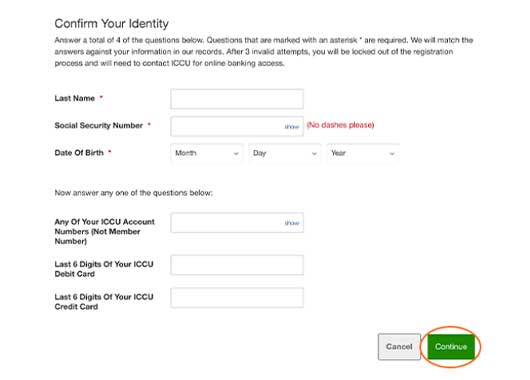
Ready to take the plunge? Begin by visiting an ICCU branch or the official website to complete the membership application. Bring a valid ID, proof of Idaho residency or employment, and your opening deposit. After your account is active, explore the digital tools, set up direct deposit, and consider which products align with your financial roadmap.
Don’t hesitate to ask a member service representative about introductory offers or upcoming webinars that walk new members through budgeting, credit building, and home‑buying strategies. The more you engage, the more value you’ll extract from the cooperative model.
FAQ
Can I open an account if I’m not a resident of Idaho?
Membership eligibility extends to anyone who works, attends school, or owns property in Idaho. If you have a close family member who is already a member, you may also qualify through the household relationship rule.
What’s the difference between a credit union and a traditional bank?
Credit unions like ICCU are not‑for‑profit cooperatives owned by members. This structure typically results in lower fees, better interest rates, and a focus on community rather than shareholder profit.
Are there any hidden fees I should watch for?
ICCU strives for transparency, but it’s smart to review the account agreement for fees such as out‑of‑network ATM usage or wire transfer charges. Most standard transactions are either free or modestly priced.
How does the annual dividend work?
If the credit union posts a surplus at year‑end, a portion may be distributed to members based on account balances. It appears as a credit on eligible accounts, effectively rewarding you for being an owner.