How to Navigate Tesla’s Financing Options
Buying a Tesla isn’t just about choosing a sleek electric sedan or a rugged SUV; it’s also about figuring out the most sensible way to pay for it. Tesla financing options range from traditional loans to proprietary lease programs, and each comes with its own set of perks and pitfalls. Whether you’re a first‑time EV buyer or a seasoned tech enthusiast, understanding these pathways can save you both money and headaches.
Understanding Tesla Financing Options
At a glance, Tesla offers three primary routes: a direct loan through its own financing arm, a lease tailored to electric vehicles, and the classic route of securing a loan from a bank or credit union. While the basics sound simple, the details matter. Below is a quick rundown of each path.
- Tesla Direct Loan – Managed by Tesla Finance, this loan lets you lock in a fixed interest rate at the time of purchase. Payments are typically monthly, and you can choose terms from 24 to 72 months.
- Tesla Lease – Ideal for drivers who want to upgrade every few years. Leases usually last 24 to 36 months and include mileage caps (often 10,000–15,000 miles per year). At lease end, you can either return the car, purchase it at a pre‑determined residual value, or roll into a new lease.
- Third‑Party Financing – Traditional lenders may offer competitive rates, especially if you have an excellent credit score or existing relationship with the bank. This route gives you flexibility to refinance later if rates drop.
What Sets Tesla’s Own Financing Apart?
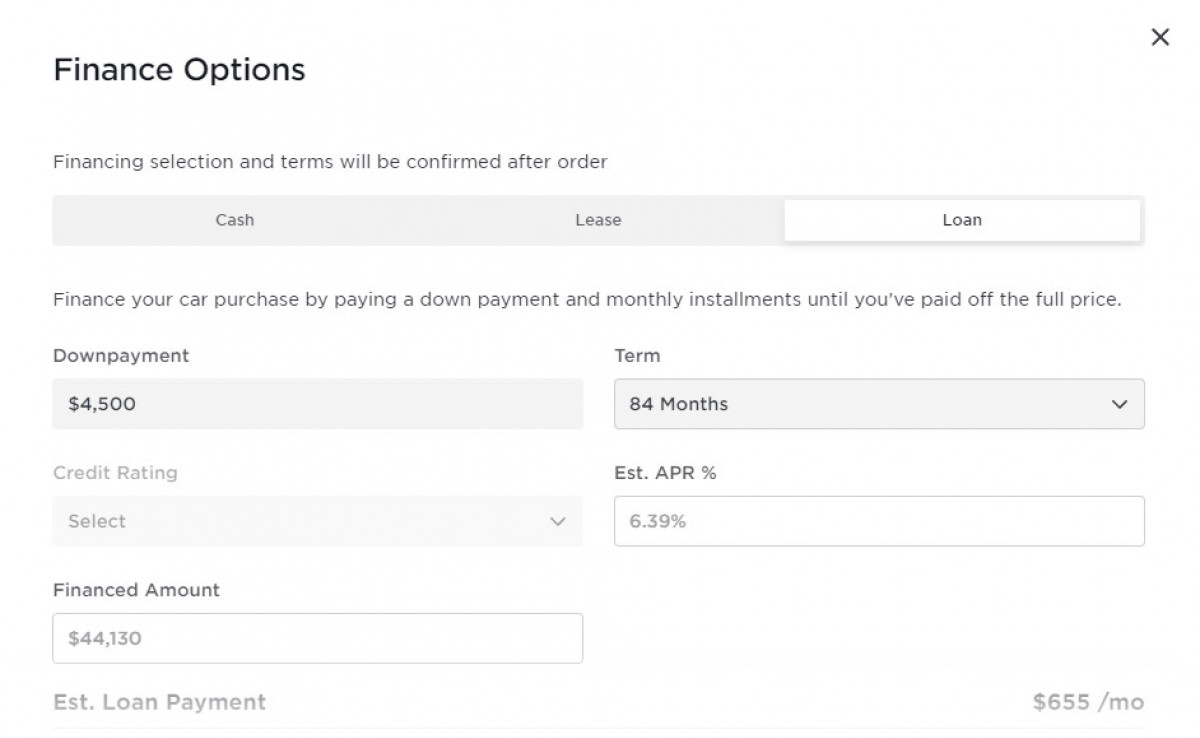
Because Tesla handles financing in‑house, the application process is fully integrated into the online configurator. You can receive a preliminary rate within minutes, adjust the down payment, and instantly see how it impacts your monthly cost. The trade‑off is that Tesla’s rates can be slightly higher than the best bank offers, particularly for borrowers with stellar credit.
Another perk is the “Tesla Wallet” integration, which allows you to link your payment method and track payments directly from the mobile app. This level of transparency is rare with conventional lenders.
When a Lease Makes Sense
Leasing is often the go‑to for drivers who love the idea of a new car every few years without the hassle of selling a used vehicle. Tesla’s lease structure includes a few nuances worth noting:
- Maintenance is generally covered under the basic warranty, but you’re still responsible for tire wear and any damage beyond normal wear.
- Early termination can be costly; you’ll typically owe the remaining lease balance plus an early‑termination fee.
- At the end of the lease, the residual value is set when you sign the agreement. If the market value of the vehicle exceeds this figure, buying it outright can be a smart move.
How to Secure the Best Rate
Regardless of which financing path you choose, a few universal strategies can improve your odds of landing a favorable rate:
- Check Your Credit Score – Most lenders require a minimum FICO of 620 for a loan, but a score above 720 usually unlocks the best rates.
- Shop Around – Even if you’re leaning toward Tesla’s loan, get pre‑approval quotes from at least two banks. A small difference in interest can translate into thousands saved over the life of the loan.
- Increase Your Down Payment – Putting down 20 % or more lowers your loan‑to‑value ratio, which lenders view as less risky.
- Consider Incentives – Federal tax credits, state rebates, and even utility company incentives can effectively reduce the purchase price, improving the financing terms you qualify for.
Special Considerations for EV Buyers
Electric vehicles bring unique financial factors. Many states offer additional rebates that are applied after the purchase, meaning you might need to finance the full price upfront and receive the rebate later. Also, the depreciation curve for Teslas has historically been flatter than for internal‑combustion cars, which can make leasing or buying a used Tesla an attractive option.
Insurance costs can be higher due to repair expenses for the battery and advanced electronics. Some lenders factor anticipated insurance premiums into the loan amount, so be sure to request a clear breakdown.
Comparing the Numbers: Loan vs. Lease
To illustrate the difference, imagine a 2024 Model 3 Standard Range Plus priced at $44,990. With a 10 % down payment, a 60‑month Tesla direct loan at a 4.9 % APR would result in a monthly payment of about $724. In contrast, a 36‑month lease with a $4,500 capitalized cost reduction (effectively the down payment) might come out to $499 per month, but you’d be limited to 12,000 miles per year and owe a residual value of roughly $26,000 if you decide to buy at lease end.
These figures are illustrative; your actual rates will hinge on credit, location, and any applicable incentives. Still, the comparison highlights a key point: leasing lowers short‑term cash outflow but can be more expensive in the long run if you intend to keep the vehicle.
Steps to Apply for Tesla Financing
Ready to move forward? Follow these straightforward steps, whether you opt for Tesla’s loan or a third‑party lender:
- Configure your desired Tesla online, selecting trim, color, and any upgrades.
- When you reach the “Payment” screen, click “Financing” and choose either “Tesla Loan” or “Tesla Lease.”
- Enter personal details, upload proof of income, and consent to a credit check. The process typically takes under ten minutes.
- If you prefer a bank loan, request a pre‑approval letter before finalizing the order. You can then input the loan amount during checkout.
- Review the contract, paying close attention to interest rate, term length, and any fees. Sign electronically and set up automatic payments to avoid late fees.
Common Pitfalls to Avoid
Even seasoned buyers can stumble. Here are a few traps that catch many Tesla purchasers off guard:
- Overlooking Mileage Limits – Exceeding the lease mileage allowance triggers steep per‑mile penalties, sometimes over $0.30 per extra mile.
- Ignoring Early‑Payoff Fees – Some Tesla loans include a prepayment penalty. Double‑check the terms before deciding to pay off the balance early.
- Neglecting Incentive Timing – State rebates may require you to submit paperwork within a specific window after purchase. Missing the deadline can erode the financial benefit you anticipated.
- Assuming “Zero Down” Is Free – Zero‑down financing often comes with higher interest rates, which can increase total interest paid by several hundred dollars.
Frequently Asked Questions
Do I need a high credit score to lease a Tesla?
While Tesla doesn’t publish a strict minimum, most lessees have a FICO score of 680 or higher. A stronger credit profile typically secures a lower money‑factor, which translates into lower monthly payments.
Can I refinance my Tesla loan later?
Yes. Many owners refinance after a year or two if market rates drop. Since Tesla loans are conventional installment loans, you can work with any lender that accepts auto loan refinancing.
Are there any hidden fees in Tesla financing?
Standard fees include a documentation fee (usually $250) and, for leases, a disposition fee at lease end (around $350). Tesla is transparent about these costs during the checkout process, but always read the fine print.
What happens if I want to sell my Tesla before the loan is paid off?
You can sell the car, but you’ll need to pay off the remaining loan balance first. If the sale price exceeds the loan payoff amount, the excess goes to you; otherwise, you’ll owe the difference.