How to Score the Best Hyundai Kona Financing Deals
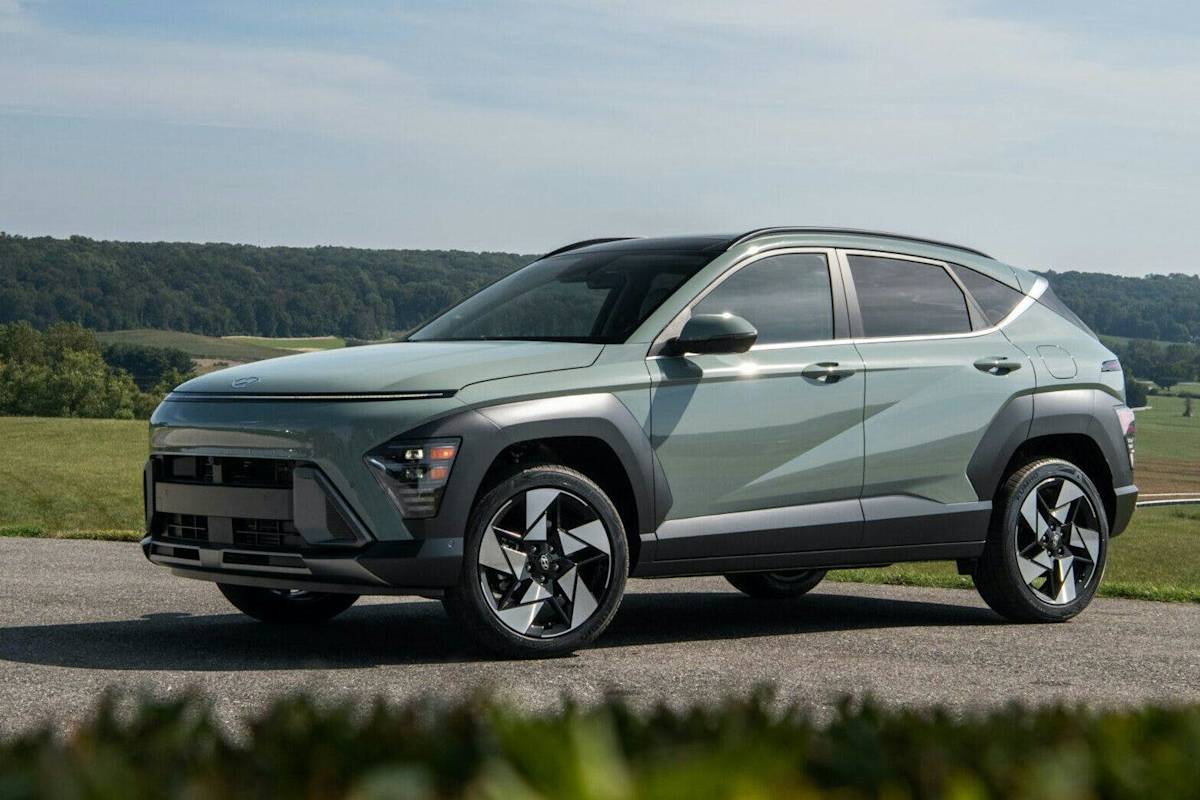
The Hyundai Kona has become a favorite for those wanting a compact SUV that doesn’t skimp on style or technology. When you’re ready to take one home, the financing offer you lock in can shave hundreds, sometimes thousands, off your total cost. This guide walks you through the key options, how to spot the best rates, and what to watch out for when you’re comparing offers.
Why Financing Matters for the Kona
Financing isn’t just about paying off a vehicle; it’s about the total cost you’ll pay over time. A lower interest rate, a shorter loan term, or a larger down payment can all influence the overall expense. For the Kona, whose MSRP hovers in the mid‑$20,000s, even a small change in the annual percentage rate (APR) can add or subtract several hundred dollars each year.
Types of Financing Deals You’ll Encounter
When you visit a dealership or search online, you’ll typically see three main categories of offers:
- Manufacturer Incentives – These are special rates or rebates Hyundai offers directly to consumers. They often require you to use a specific lender or meet certain credit criteria.
- Dealer Financing Packages – Dealers partner with banks or credit unions to provide loans with unique terms. They sometimes include “buy‑here, pay here” plans with flexible down payment options.
- Credit Union Rates – If you’re a member of a credit union, you can often secure a lower APR because these institutions usually charge less than commercial banks.
Manufacturer Incentives: What to Look For
Hyundai occasionally rolls out “zero‑interest” or “low‑APR” packages for qualified buyers. These deals are typically tied to specific model years and trim levels. To qualify, you’ll usually need:
- A minimum credit score (often around 640‑680).
- A down payment that covers a certain percentage of the vehicle’s price.
- A commitment to a loan term no longer than the incentive’s maximum length (often 48 months).
If you meet these conditions, the lender may cover the interest, letting you pay only the principal plus any applicable taxes and fees.
Dealer Financing: Flexibility vs. Cost
Dealers can offer quick approval and convenient paperwork. The catch? The interest rates can sometimes be higher than those offered through a credit union or the manufacturer’s direct program. Always ask for a written statement of the APR and any fees that will be applied.
Credit Union Advantage
Credit unions operate on a not‑for‑profit model, meaning they can pass savings onto members. If you’re eligible, a credit union can often match or beat the manufacturer’s incentive rates. The process typically involves:
- Verifying your membership status.
- Submitting your credit profile.
- Negotiating a term that fits your budget.
Because the rates are usually lower, the total interest paid over the life of the loan decreases significantly.
Step‑by‑Step: Securing the Deal
Follow these steps to ensure you’re getting the best possible financing for your Kona:
- Check Your Credit Score – Get a free credit report from the major bureaus and identify any errors.
- Research Current Incentives – Visit Hyundai’s official site or reputable automotive sites that list the latest financing offers.
- Compare Lender Options – Use online calculators to see how different APRs and terms affect monthly payments.
- Ask for a Detailed Quote – Request a written offer that lists the APR, loan term, down payment, and any hidden fees.
- Negotiate – Don’t accept the first quote. Use competing offers as leverage.
- Finalize the Loan – Review the contract carefully before signing, ensuring the terms match the agreed-upon numbers.
Common Pitfalls to Avoid
Even seasoned buyers can fall into traps that inflate the Kona’s true cost:
- Skipping the Rate Lock – If you’re waiting for a better rate, the lender might change terms before you finalize.
- Over‑financing the Vehicle – Adding extra warranties or services can raise the loan amount without lowering the monthly payment.
- Ignoring Hidden Fees – Some dealers tack on documentation fees, title fees, or pre‑payment penalties. These can add up.
- Neglecting the Total Cost of Ownership – Beyond financing, consider insurance, maintenance, and fuel costs to get the full picture.
FAQs About Hyundai Kona Financing Deals
What credit score do I need to qualify for a Hyundai incentive?
Most manufacturer incentives require a minimum score of 640‑680, though this varies by offer.
Can I use a credit union loan even if the Kona is only available at a dealer?
Yes. If you’re a credit union member, you can negotiate a loan directly with the institution and then use that financing through the dealer’s paperwork.
Are there any hidden costs I should watch for?
Look out for documentation fees, title fees, and any extended warranty add‑ons that can increase the loan amount without affecting the monthly payment.
How can I make my monthly payment lower without extending the loan term too much?
A larger down payment reduces the principal, thereby lowering monthly payments. Alternatively, a slightly higher APR may still produce a lower payment if the loan term is significantly shorter.
By understanding the various financing routes and approaching each deal with a clear strategy, you can confidently drive off the lot in a Hyundai Kona with a payment plan that fits your budget.