How USAA Auto Loans Work: Rates, Terms, and Applying Made Simple
Finding the right car loan can feel like a maze, but with a little guidance, the path gets clearer. USAA, the credit union that serves active‑duty, retired, and veteran families, offers auto loans with competitive rates and flexible terms. This article breaks down what you can expect from USAA auto loans, the qualifications that matter, and a step‑by‑step look at how to apply.
USAA Auto Loan Rates: What to Expect
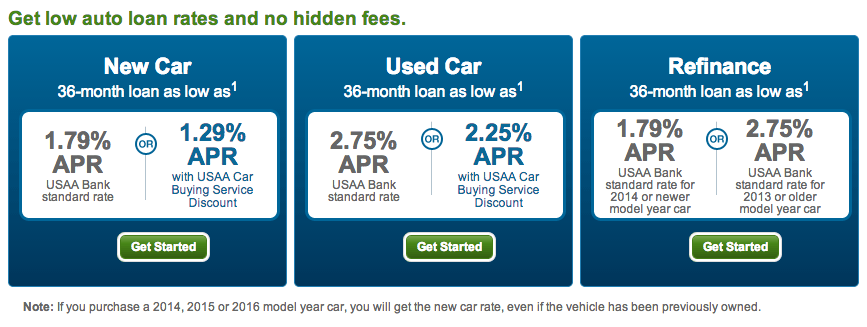
USAA’s auto loan rates are typically anchored to the prime rate plus a small margin that reflects the borrower’s credit profile. As of early 2026, the average APR ranges from 3.5% to 7.5%, depending on the loan amount and term length. Military members and retirees often enjoy the lower end of that spectrum because of the credit union’s favorable underwriting standards for those with a service record.
Because USAA is a nonprofit credit union, the savings on interest can be significant compared to traditional banks. For instance, a $25,000 loan at a 5% APR over 60 months translates to roughly $47 per month in interest, whereas a comparable loan at a 9% APR could cost you an extra $30 per month.
Rates are not fixed forever; they can shift with market conditions. It’s a good idea to lock in a rate when you’re ready to purchase. USAA offers “rate‑lock” options for members who qualify, allowing you to secure a rate for a set period while you finalize vehicle paperwork.
Terms, Eligibility, and Credit Considerations
USAA auto loans come in terms ranging from 36 to 84 months, giving borrowers flexibility to balance monthly payments against total interest paid. Shorter terms reduce interest but raise monthly obligations; longer terms lower the monthly bill at the cost of higher total interest.
Eligibility hinges on a few key factors:
- Membership status: Active, retired, or family of military members.
- Credit score: While USAA is forgiving, a score above 680 usually secures the best rates.
- Employment: Stable income and a verifiable employment history enhance approval odds.
- Debt‑to‑income ratio: A lower ratio demonstrates financial health and eases underwriting.
USAA also considers the vehicle’s age and condition. Most loans cover cars up to five years old, but newer models can still qualify if they meet depreciation guidelines.
Step‑by‑Step Guide to Applying for a USAA Auto Loan
While the process is straightforward, knowing the steps in advance can save time and reduce surprises.
Pre‑Application Checklist
- Verify USAA membership or apply for one if you’re eligible.
- Check your credit score with a free report.
- Determine how much you can afford for a down payment and monthly payment.
- Gather employment documentation and proof of income.
- Choose a vehicle and obtain a recent invoice or purchase agreement.
Online Application Process
- Log in to your USAA account: Navigate to the “Auto” section under “Loans.” If you’re a new member, you’ll need to create an account first.
- Enter vehicle information: Provide make, model, year, VIN, and purchase price.
- Select loan term: Pick between 36 and 84 months.
- Submit required documents: Upload proof of income, employment, and, if applicable, a vehicle title or dealer invoice.
- Review the offer: USAA will present an APR and monthly payment estimate based on your inputs.
- Accept the offer or negotiate: If the terms aren’t to your liking, you can request a different term or down‑payment amount.
- Sign electronically: Complete the e‑signature to finalize the loan agreement.
In‑Person and Phone Options
If you prefer face‑to‑face interaction, USAA’s branch network—primarily located in military bases and service communities—offers loan officers who can walk you through the process. Alternatively, you can call the USAA customer service line to start a conversation; they’ll guide you to an online or in‑branch path that suits your schedule.
Frequently Asked Questions
- Does USAA offer pre‑approval for auto loans? Yes. Members can receive a pre‑approval letter that outlines the maximum loan amount and rate, giving them a clear budget before shopping.
- Can I pay off my loan early? Early repayment is allowed, and many members take advantage of it to save on interest. Check for any pre‑payment penalties, though USAA typically does not impose them.
- What happens if I miss a payment? USAA’s policy is to give a brief grace period before penalties apply. Contacting the loan servicer early can help you avoid late fees.
- Is auto insurance required for the loan? Yes. USAA requires full‑coverage insurance on the financed vehicle to protect both the borrower and the lender.