Navigating Iowa College Financing: A Straight‑Forward Roadmap
Choosing a college in Iowa is just the first step; figuring out how to pay for it can feel like a maze. Iowa college financing isn’t a mystery if you break it down into manageable parts. This guide pulls back the curtain on the tools, programs, and strategies that make higher education affordable for Iowa families.
Why Iowa College Financing Matters
Iowa students and parents often overlook the state’s unique financing options. Understanding how Iowa college financing works early can shave thousands off a student’s debt load. It’s not just about scholarships; it’s a mix of grants, work‑study, and state savings plans that many overlook.
Key Funding Sources
There are three primary categories to consider:
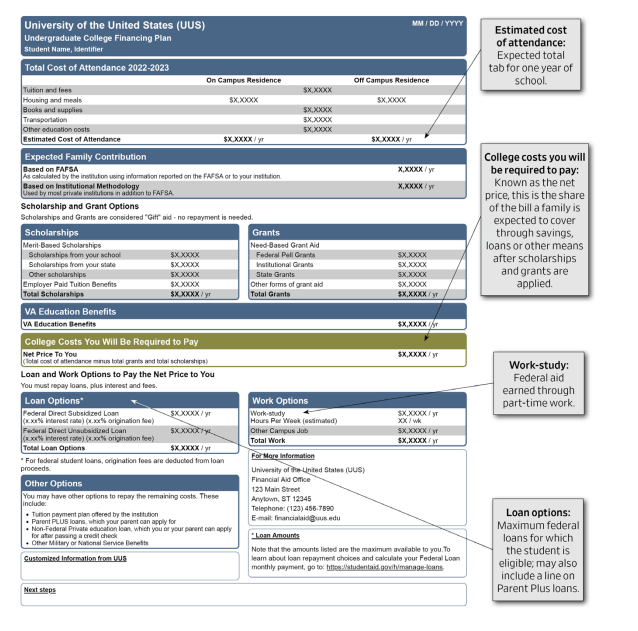
- Federal aid – The FAFSA unlocks Pell Grants, Direct Subsidized and Unsubsidized Loans, and PLUS Loans.
- State aid – The Iowa Grant Program offers need‑based assistance that often tops federal aid for in‑state residents.
- Institutional aid – Colleges award their own scholarships and tuition waivers, sometimes based on merit or specific criteria.
Each stream has its own application process and deadlines, so coordinating them is key.
Applying for Scholarships and Grants
Scholarships in Iowa range from statewide programs to local foundations. Start with the University of Iowa Scholarship Database and the Iowa Board of Regents Scholarship Search. When you find opportunities, read the eligibility carefully; many scholarships require a minimum GPA, a specific major, or community service involvement.
Grants, on the other hand, do not need to be repaid. The Iowa Grant Program offers up to $4,800 for qualified students who demonstrate financial need and meet GPA requirements. The application is free and can be filed with the FAFSA, so it’s often a first stop.
Student Loans: Federal vs. Private
Once grants and scholarships cover the gap, loans typically fill the remaining amount. Federal loans are usually more favorable:
- Direct Subsidized Loans – No interest while you’re enrolled full‑time.
- Direct Unsubsidized Loans – Interest accrues from the start, but you can defer payments.
- PLUS Loans – For parents or graduate students, with higher interest rates.
Private lenders often offer lower interest rates but may lack borrower protections. Compare rates, repayment plans, and potential forgiveness options before committing.
Choosing the Right Repayment Plan
Federal repayment plans include Standard, Graduated, and Income‑Driven options. Income‑Driven plans adjust your monthly payment to a percentage of discretionary income, which can be a lifesaver if your post‑grad earnings are modest. Private loans usually have fixed payments, so plan accordingly.
Budgeting Tips for Iowa College Students
Managing expenses is as crucial as securing funding. Here are practical steps:
- Track daily spending with a simple spreadsheet or app.
- Live in dormitories or shared apartments to keep rent low.
- Use university grocery discounts and buy in bulk.
- Plan for unexpected costs like travel or medical emergencies by setting aside a small emergency fund.
Small habits add up; disciplined budgeting reduces the need for additional loans.
Work‑Study and Part‑Time Jobs
Iowa offers work‑study positions that let students earn money on campus. These jobs pay the hourly wage set by the university and don’t affect federal aid eligibility. Additionally, many local businesses hire students for part‑time roles, which can help cover books or personal expenses.
When choosing a job, prioritize flexibility so it doesn’t interfere with your coursework. A well‑balanced schedule keeps grades up and stress low.
Saving for College in Iowa: State Programs
The Iowa College Tuition Savings Plan lets families invest early. Contributions grow tax‑deferred, and withdrawals for qualified education expenses are tax‑free. While it’s a long‑term strategy, it can significantly reduce out‑of‑pocket costs when the student reaches college age.
Another option is the Iowa 529 Savings Plan, which offers state tax deductions for contributions. If you’re a first‑generation student, these plans can smooth the financial transition.
Keeping Track of Your Finances
Use a dedicated notebook or digital tool to record every dollar that comes in and goes out. Update it weekly, and review your budget monthly. Pay attention to credit card balances, loan interest accruals, and upcoming bill due dates. Staying on top of your money prevents surprises and keeps you in control.
Common Pitfalls to Avoid
Many students fall into traps that inflate their debt:
- Overestimating need for loans while ignoring grants.
- Skipping the FAFSA—over 60% of students submit it late or not at all.
- Failing to understand the terms of private loans, which can come with higher rates and fewer protections.
- Ignoring the value of early savings; the sooner you start, the more you earn in compound interest.
Being proactive and informed is your best defense against financial overload.
Frequently Asked Questions
What is the deadline for the Iowa Grant Program? The Iowa Grant Program typically closes on the same day as the federal FAFSA, which is September 30 for most years, but check each academic year’s specific deadline.
Can I combine multiple scholarships and grants? Yes, scholarships and grants stack. However, remember that most scholarships and grants count toward the total aid package and can affect the amount of federal student aid you qualify for.
Is it worth taking a private loan if I have federal aid? Usually, federal aid offers more borrower protections and lower rates. Private loans should only be considered if federal aid does not cover all costs and if you are comfortable with the terms.
How early should I start saving for college in Iowa? Beginning as soon as possible maximizes the benefits of compound interest and state tax deductions. Even small monthly contributions can grow substantially over 10 to 18 years.